The Difference Between Looking Rich and Actually Being Rich
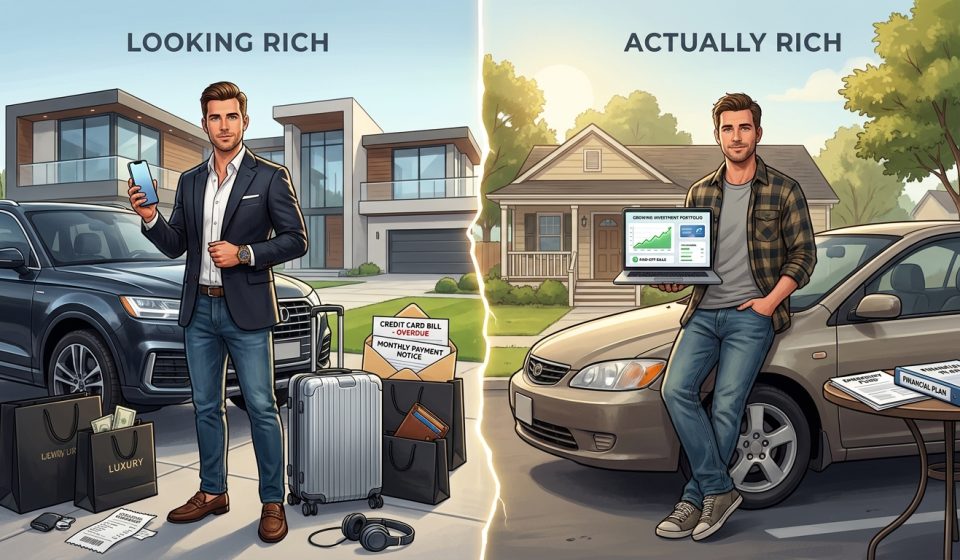
There are people who look rich everywhere.
The expensive SUV. The designer clothes. The newest iPhone. The impressive apartment. The weekend trips. The restaurant photos.
And then there are people who are quietly building wealth.
You may not notice them.
They might drive a five-year-old car, live in an ordinary neighborhood, wear the same clothes they’ve had for years, and think twice before upgrading a perfectly good phone.
From the outside, the first person may appear wealthier.
But appearances can be remarkably bad at measuring financial health.
The real difference between looking rich and actually being rich has much less to do with what someone owns and much more to do with what they keep.
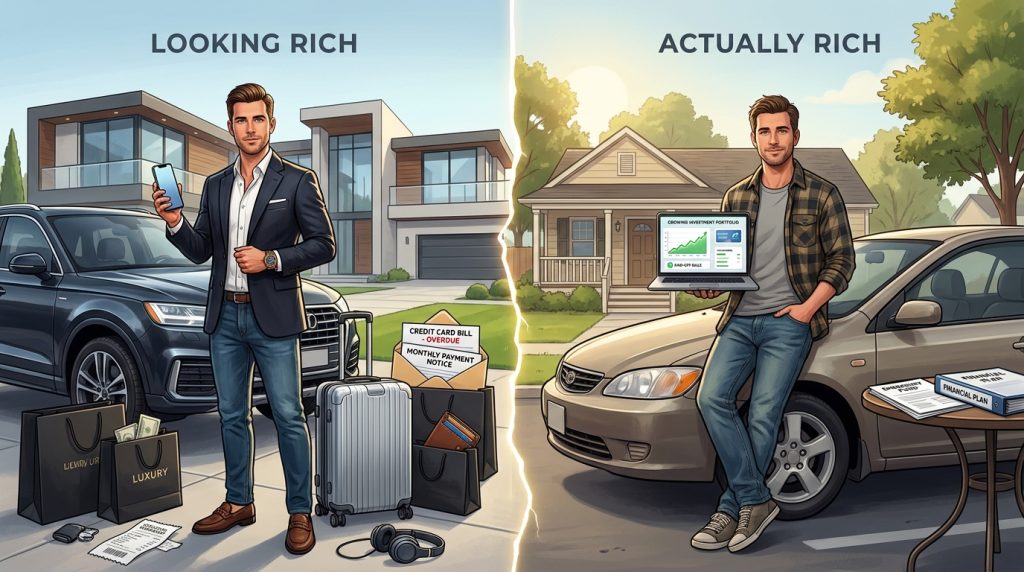
Looking rich is about consumption. Wealth is about ownership.
One of the easiest ways to look wealthy is to spend money.
Buy the expensive car and people can see it.
Move into the luxury apartment and people can see it.
Wear the expensive watch and people can see it.
The problem is that consumption tells you very little about someone’s actual financial position.
A person can have a $70,000 vehicle sitting in the driveway and very little money in the bank.
Another person might have hundreds of thousands of dollars invested and drive a used Toyota.
You can’t tell which person is wealthier by looking at the driveway.
That’s because wealth is largely about assets minus liabilities.
Someone who owns valuable assets but has relatively little debt may have substantial net worth. Someone surrounded by expensive possessions that are heavily financed may have far less financial security than their lifestyle suggests.
The Federal Reserve’s latest Survey of Consumer Finances found that U.S. family net worth increased substantially between 2019 and 2022, but the distribution of wealth remained highly uneven. The survey also found that more than 45% of families reported carrying a credit-card balance after their most recent payment in 2022.
The lesson isn’t that expensive things are bad.
It’s that expensive things aren’t the same thing as wealth.
The person with the nicer car may not be richer
Cars are one of the clearest examples.
Suppose two people earn similar incomes.
Person A buys a brand-new luxury SUV and takes on a large monthly payment.
Person B buys a reliable three-year-old car and keeps the difference available for savings, investing, or other goals.
From the outside, Person A looks wealthier.
But if Person B is steadily accumulating financial assets while Person A is committing a large portion of income to transportation, their financial positions could look very different after several years.
This is where lifestyle choices become important.
The expensive car isn’t necessarily a bad decision. Someone may genuinely value it and comfortably afford it.
The problem is when the appearance of success consumes the money that could have created actual financial independence.

Wealth gives you options
Here’s a useful way to think about the difference.
Looking rich gives you things.
Being wealthy gives you options.
If you have substantial savings and investments, you may be able to leave a terrible job without immediately panicking about your next paycheck.
You may be able to handle a major car repair without putting it on a credit card.
You may be able to take several months to make an important career decision.
You may be able to help a family member.
You may be able to turn down an opportunity that isn’t right for you.
That flexibility is one of the most useful forms of wealth.
The Federal Reserve’s 2025 household survey found that 63% of U.S. adults said they could cover a hypothetical $400 emergency using cash, savings, or a credit card they could pay off at the next statement. But only 55% said they had emergency savings sufficient to cover three months of expenses.
Having money doesn’t just mean being able to buy more.
It means being less vulnerable when something goes wrong.
The wealthy-looking person often has a much bigger monthly burn rate
There’s another difference that is easy to miss.
Two people can earn the same amount of money but have completely different financial lives.
Imagine two Americans each take home $7,000 a month.
The first spends $6,700.
The second spends $4,500.
On Instagram, the first person might look considerably wealthier.
They eat at expensive restaurants. They travel more. They drive a newer car. Their apartment is nicer.
But the second person has $2,500 of monthly breathing room.
That margin matters.
It can become savings.
It can become investments.
It can pay down debt.
It can fund a business.
It can sit there as protection against the unexpected.
The Consumer Financial Protection Bureau recommends looking at actual spending over several months, including irregular expenses that are easy to forget, rather than relying on a rough mental estimate of where your money goes.
That’s because financial strength is often hiding inside the gap between what you earn and what you need to spend.
Looking rich often requires other people to notice
This is where money becomes psychological.
Sometimes we’re not buying something because we love it.
We’re buying it because of what it communicates.
A luxury watch can communicate success.
A new car can communicate status.
A large house can communicate achievement.
An expensive vacation can communicate that life is going well.
There is nothing inherently wrong with any of this.
Humans naturally care about status and social signals.
But the problem begins when financial decisions are made primarily for an audience.
Because the audience doesn’t have to pay the bill.
You do.
Real wealth can look surprisingly ordinary
One of the stranger things about wealth is that it can become less visible as it grows.
Someone who is financially secure doesn’t necessarily need to announce it.
They may still buy expensive things.
But they don’t need every purchase to prove something.
They can buy a $5 coffee without worrying that it will ruin their finances.
They can buy a luxury car if they genuinely want one and can comfortably afford it.
They can also keep the same car for ten years if that makes more sense.
The difference is choice.
When your lifestyle depends on maintaining a certain image, your spending can become a requirement.
When you have financial security, spending becomes more of a choice.
That distinction is easy to miss.
The richest person in the room may not look like it
There’s a reason financial advice often talks about net worth instead of income.
Income tells you how much money is coming in.
Net worth tells you what has accumulated after considering what you owe.
A high income can disappear through high spending.
A moderate income can produce substantial wealth if a person consistently spends below their means and accumulates assets over time.
Of course, income matters. It is much easier to build wealth when you have more money available after essential expenses.
But income alone doesn’t determine financial security.
Consider someone earning $200,000 a year who spends nearly all of it.
Now consider someone earning $90,000 who consistently saves and invests a meaningful portion of their income for decades.
Their lifestyles may look completely different.
And so may their eventual financial positions.
The Federal Reserve’s 2022 Survey of Consumer Finances found that the median net worth of U.S. families was $192,900, while mean net worth was much higher at $1.06 million, illustrating how a relatively small number of very wealthy households can pull the average upward.
The number on someone’s paycheck therefore tells only part of the story.
Wealth is often built by doing boring things repeatedly
The internet makes wealth look exciting.
There’s the stock-market screenshot.
The luxury car.
The beach house.
The entrepreneur celebrating a huge exit.
The investment that supposedly turned $1,000 into $100,000.
But most sustainable wealth-building is much less cinematic.
Someone earns money.
They spend less than they earn.
They maintain an emergency reserve.
They pay attention to expensive debt.
They invest consistently.
They increase their savings when their income rises.
They avoid repeatedly resetting their lifestyle every time they get a raise.
Then they do it again.
And again.
And again.
Compounding rewards time and consistency, which is one reason starting earlier can matter even when the initial amounts are relatively small.
The Federal Reserve’s 2025 survey found that people who consistently had money left over at the end of the month were much more likely to report having enough savings to cover three months of expenses. Among adults who said they always had money left over, 86% reported having such emergency savings, compared with 13% among those who never had money left over.
There is nothing glamorous about that.
But it works in the background.

The goal isn’t to look poor
There’s an important distinction here.
Being wealthy doesn’t mean refusing to spend money.
It doesn’t mean driving an old car forever, never traveling, buying the cheapest clothes, or feeling guilty whenever you enjoy something.
That’s just another form of financial extremism.
If you genuinely value something and can afford it without damaging your long-term finances, spending money on it can be perfectly reasonable.
The question is different:
Are you buying it because you can afford it, or because you need other people to think you can afford it?
Those are very different motivations.
A person with real wealth can spend freely in areas that matter to them while being disciplined in areas that don’t.
They don’t have to optimize every dollar.
They simply understand what their money is doing.
A simple test for real financial wealth
Forget the car.
Forget the watch.
Forget the house.
Forget what someone’s social media looks like.
Ask a few quieter questions.
Could they handle an unexpected $1,000 expense without going into expensive debt?
Do they have savings?
Do they own investments or other productive assets?
Are they carrying expensive consumer debt?
Does their lifestyle require every paycheck to arrive on time?
Could they survive a period without income?
Are they building assets faster than their lifestyle is becoming expensive?
And perhaps the most revealing question:
If nobody else could see their possessions, would their financial decisions change?
That’s where the difference becomes clearer.
The quiet advantage of not needing to look rich
Looking rich can be expensive because it requires maintenance.
The car needs payments, insurance, fuel and maintenance.
The larger home needs a larger mortgage or rent, utilities and upkeep.
The designer wardrobe needs replacing.
The lifestyle creates expectations.
Real wealth doesn’t have to perform.
It can sit quietly in an investment account.
It can exist as a paid-off home.
It can be an emergency fund nobody else knows about.
It can be the ability to walk away from a bad situation.
It can be the freedom to say, “No, I don’t need that.”
And perhaps that’s the biggest difference.
Looking rich is about what your money can make other people think about you.
Being rich is about what your money allows you to do with your life.
One is visible.
The other is freedom.
And if you had to choose between the two, the second one is the much better deal.


